

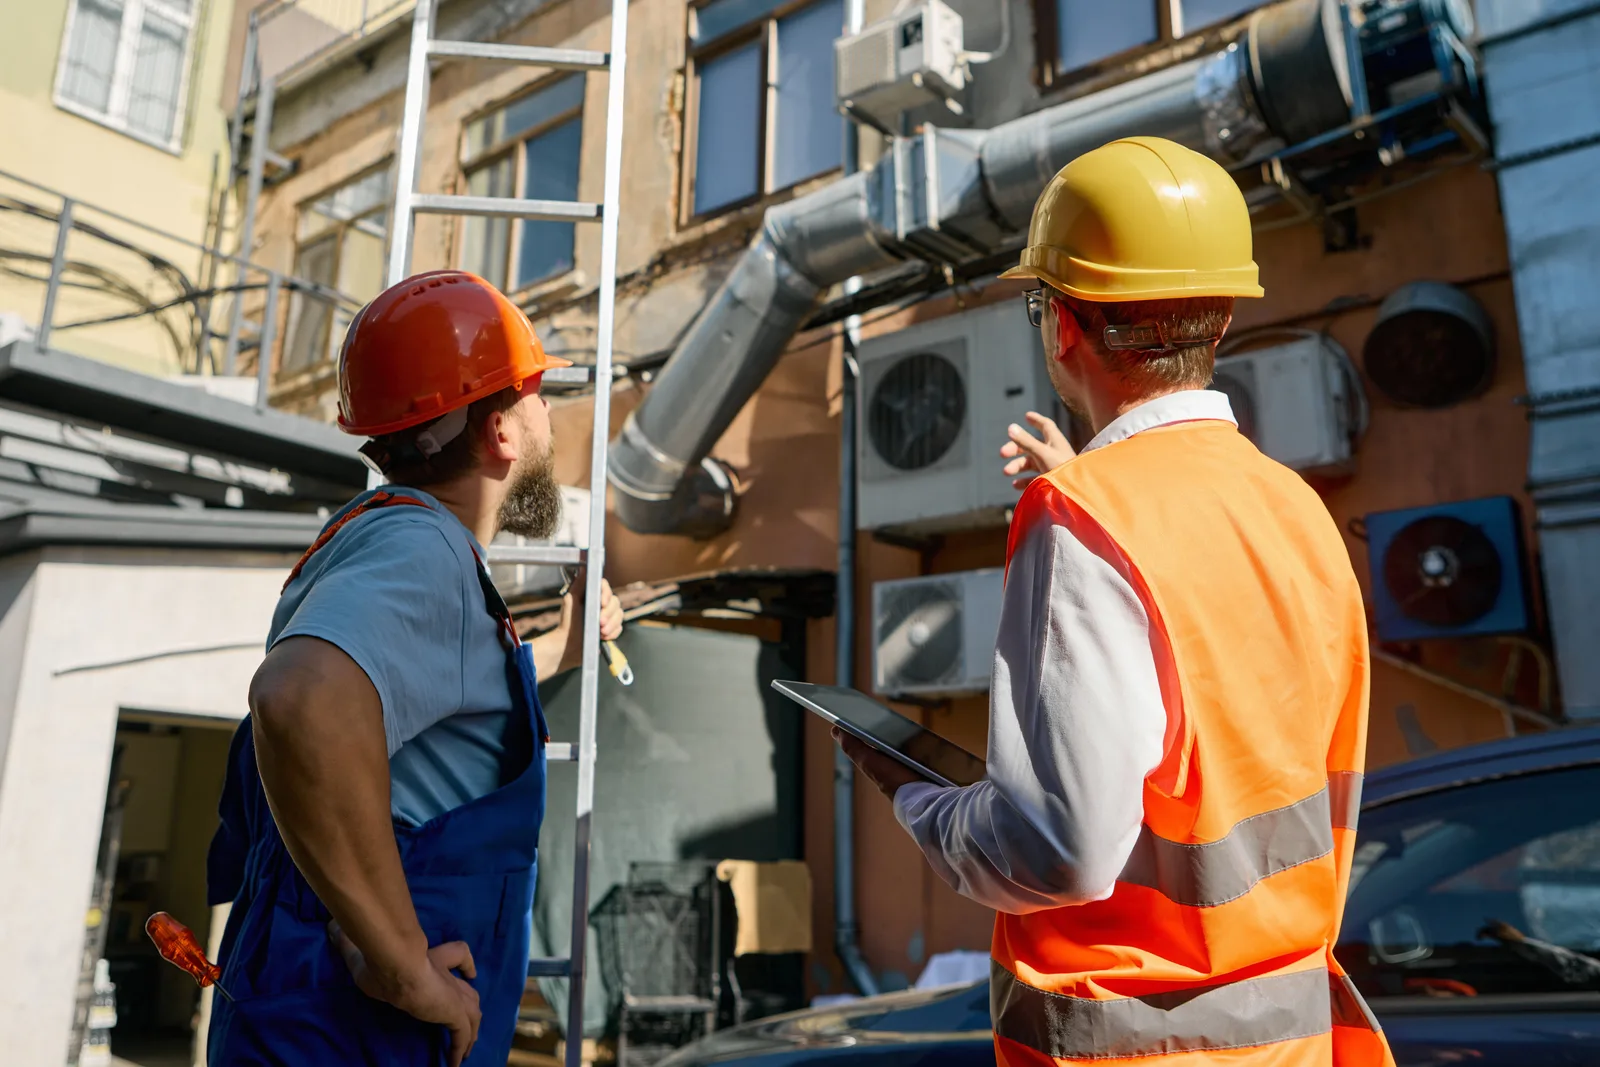
Aircraft HVAC technician insurance depends on one question: do you work on the hangar’s heating and cooling, or on the aircraft’s own air system? Hangar work is building work, where an HVAC contractor program is the starting point. Aircraft work falls under federal aviation maintenance rules, so ask whether your policy fits. This is general education, not legal advice.
What does “aircraft HVAC technician” mean for insurance?
It can mean three different jobs, and the insurance conversation is different for each. The search phrase does not say which one, so sort yourself first.
The first is building work. A hangar, a terminal or a maintenance shop needs heating, cooling and ventilation like any large building, and an HVAC contractor installs and services it. The second is ground equipment that sits outside the aircraft and feeds conditioned air to it through a hose while it is parked. The third is the aircraft’s own environmental system, the equipment that travels with the airplane.
A contractor’s program, described on our HVAC contractor insurance page, is designed around the first job. The further you move toward the third, the more the work looks like aviation maintenance and the less it looks like a building trade. Tell your agent which of the three you do, in those plain words.
What changes when you work on the aircraft itself?
The work moves under a federal rulebook that has nothing to do with building codes. Federal aviation rules on aircraft maintenance are in 14 CFR Part 43, which is titled maintenance, preventive maintenance, rebuilding, and alteration.
The FAA also publishes a page on how to become an aviation mechanic and a page for repair stations. We are pointing to those pages so you know where the rules sit. We have not summarized them, and we are not saying which rule applies to a given task. Whether a job counts as aircraft maintenance, and who may sign for it, is a question for the FAA, the aircraft owner or the repair station.
The middle case, ground equipment, deserves its own question. A cart or a fixed unit that sends conditioned air through a hose to a parked aircraft is not part of the aircraft, but it is connected to one while it runs. If you service that equipment, ask the airport or the operator who owns it, what rules they apply to it, and who is responsible if the aircraft is affected. Then give your agent the same facts and ask which side of the line your policy puts it on.
For insurance, the point is simpler. An EPA refrigerant card and a state mechanical license describe a building trade. If you are asked to work on an aircraft, treat it as a different line of work until someone with authority tells you otherwise, and tell your agent before you say yes.
Why might a contractor’s general liability policy not fit aircraft work?
Because the policy was priced and written for the work you described, and you described a building trade. General liability is usually explained as coverage for bodily injury and property damage your work causes to others. That description says nothing about whether aircraft work is inside the policy.
Two things can get in the way. The first is the application. If it says heating and air conditioning contractor and the loss comes from an aircraft system, expect questions. The second is exclusions. Some policies carry wording that mentions aircraft or aviation products. We did not find an official source that says how common that wording is or how it applies, so we make no claim about your policy.
Aviation risks are generally placed in a specialty insurance market with its own policies. If any part of your work is on the aircraft side, ask your agent whether your current program addresses it or whether it belongs with an agent who works in that market. Ask the same question about finished work, and read our post on completed operations coverage for HVAC first so the term is familiar.
What about aircraft parked in the hangar while you work on the building?
Even pure building work changes when the building is full of aircraft. A dropped tool, a lift that swings wide, or a leak from overhead piping can damage property that belongs to someone else and costs far more than the unit you came to service.
That is a property damage question under general liability, and it comes with two follow-ups for your agent. First, are your limits sized for the setting? If not, umbrella coverage is the usual place to look, and our post on whether an HVAC business needs an umbrella policy explains how it sits over the other lines. Second, does anything on the policy limit damage to property in your care? Our riggers liability post explains that idea for lifted equipment.
You may also hear the word hangarkeepers. It is an aviation market term for coverage that concerns aircraft of others in a business’s care. We did not find a primary source that defines it, so ask your agent and the hangar operator whether it has anything to do with a visiting contractor.
Real-World Scenario: An illustration, not a real case. A contractor is hired to replace overhead heaters in a hangar. Before pricing, the contractor asks the hangar manager to move aircraft out of the work bay and confirms that in an email. The contractor sends the airport’s insurance requirements to the agent, who answers in writing which lines respond to damage in the bay. The job starts with both emails in the file.
What can hurt the crew in a hangar or on the ramp?
Height, refrigerant and traffic are the exposures to plan for. Hangar heating and ventilation equipment hangs high, so the crew works from lifts and near roof openings. OSHA’s construction rule on fall protection is at 29 CFR 1926.501. Whether it or a general industry rule governs a given job is a question for OSHA or a safety professional.
Refrigerant rules follow you into the hangar. EPA says a technician who maintains, services, repairs or disposes of equipment that could release refrigerant must be certified, and its technician certification page explains the test types.
Then there is movement. Aircraft, tugs and fuel trucks share the space outside the hangar door, and your van may be driving among them. Ask your agent how commercial auto applies when your vehicles operate on airport property. An injured employee raises a workers compensation question, so confirm that the policy describes work at heights in large buildings.
What do airports and hangar owners ask contractors to carry?
Expect a written list, and read it before you price the job. We did not find an official source that sets one standard for airport or hangar contracts, so we cannot tell you what yours will say.
Publicly owned airports buy services the way other public bodies do, and our post on government and school HVAC contractor insurance shows how public owners write their insurance exhibits. Private hangar owners and tenants write their own. The post on what commercial HVAC clients require covers the common requests.
Send the requirements to your agent as soon as you receive them. If they ask for a line or a limit you do not carry, you want to know before you bid.
Ask about access as well. Airports control who and what goes onto the field, and a hangar owner may expect your crew to be escorted or your vehicles to stay off certain areas. Those rules are not insurance terms, but breaking one can turn a routine job into a dispute, and they shape how you price the work. Get them in writing with the insurance requirements and keep the two together.
What should you ask your agent before the first hangar job?
Bring a plain description of the work and ask for written answers.
- Scope. I work on the building, on ground equipment, or on the aircraft. Is each one within what my application describes?
- Exclusions. Does any wording on my general liability policy mention aircraft or aviation products?
- Property of others. How is damage to a parked aircraft treated, and are my limits sized for it?
- Vehicles. Does my auto policy apply on airport property?
- Crew. Is work from lifts in large buildings described on my workers compensation policy?
- Tools. Are my lifts, recovery machines and instruments listed under contractors equipment?
When you have the answers, request a quote with the airport’s requirements attached. You can also read about commercial HVAC contractor coverage or see how we work.