HVAC insurance costs whatever a carrier’s rating of your specific operation produces — there is no national price, and we do not publish a premium. The number is built from a short list of drivers that apply in every state: payroll and technician class codes, your residential and commercial mix, how much of your work is install versus service, your fleet and equipment, your completed-operations and claims history, the limits your contracts demand, how much of your work happens at height, and the workers compensation system in the states where your crews work.
That answer frustrates operators who want a number, but it is the honest one, and knowing the drivers is more useful than a made-up average. A two-van residential service-and-replace shop and a commercial mechanical contractor setting rooftop units are the same trade only in name, and a carrier prices them nothing alike. This guide walks through each driver of HVAC business insurance cost, what moves it, and what you can do about it. Where a detail turns state-specific, it points you to the state cost guides and the locations directory; for the coverage lines themselves, start with the overview of HVAC contractor insurance.
Why there is no national price for HVAC insurance
A premium is the output of an underwriting model, not a sticker. The carrier takes your specific exposures — how many people you employ and what they do, the systems your work installs and services, the completed-operations tail those installs carry, your loss history, and the limits your accounts require — and prices each line against them. Change any input and the number moves. That is why a real quote requires real details, and why the most useful thing you can do is understand which inputs a carrier reads.
A national “average” is even more misleading than a state one. Climate splits the country — cooling-dominant markets run a long air-conditioning season while heating-led markets weight the calendar toward furnaces, boilers, and heat pumps — and licensing and workers compensation rules change at every state line. A blended national number bundles operations a carrier would never price the same way, across regulatory systems that do not share a structure. Learn the drivers, then read your own state’s specifics in its dedicated guide.
Payroll, technician class codes, and workers compensation
Payroll is a central driver, because it scales both your workers compensation and a large part of your general liability. The dollar figure is only half of it; the other half is the class code each technician’s payroll is assigned to. A crew doing rooftop and mechanical install is classified differently from a residential service technician, so a carrier rates each by the work it actually does, and misclassified payroll can mean overpaying — or an audit bill later. The injury profile behind the rate is real for an HVAC crew anywhere: lifting condensers and compressors, ladder and attic falls, electrical and burn injuries, and heat exposure through the cooling season. For how the class codes work in practice, see the HVAC workers comp class code and how to reduce HVAC workers comp costs.
Install versus service work
Alongside payroll, your revenue and how it breaks down is a core general-liability driver. A carrier reads not just the top-line number but how much of it is new install and changeout versus service and maintenance, because the two carry different exposures. An install puts a new system into a building and leaves a completed-operations tail behind it for years; a maintenance visit leaves a lighter one. Two operations with similar revenue can price very differently if one is install-heavy and the other runs mostly service agreements — which leads directly into the two exposures that define the trade.
Your residential-versus-commercial work mix
Your operating model may be the most underappreciated driver of all. A residential service-and-replace operation works inside occupied houses across a high volume of smaller jobs, where in-home property damage and the completed-operations tail of an install lead, and the vans and tools ride the routes all day. A commercial and mechanical operation sets rooftop units and building systems under general-contractor relationships, where the fall exposure, a building-scale completed-operations claim, and the limit requirements in the contract drive the cost. Writing both off one generic rate overcharges one side and underprotects the other. If you run both, the operation should be split by classification so each side is priced to its own exposure.
Height and rooftop work
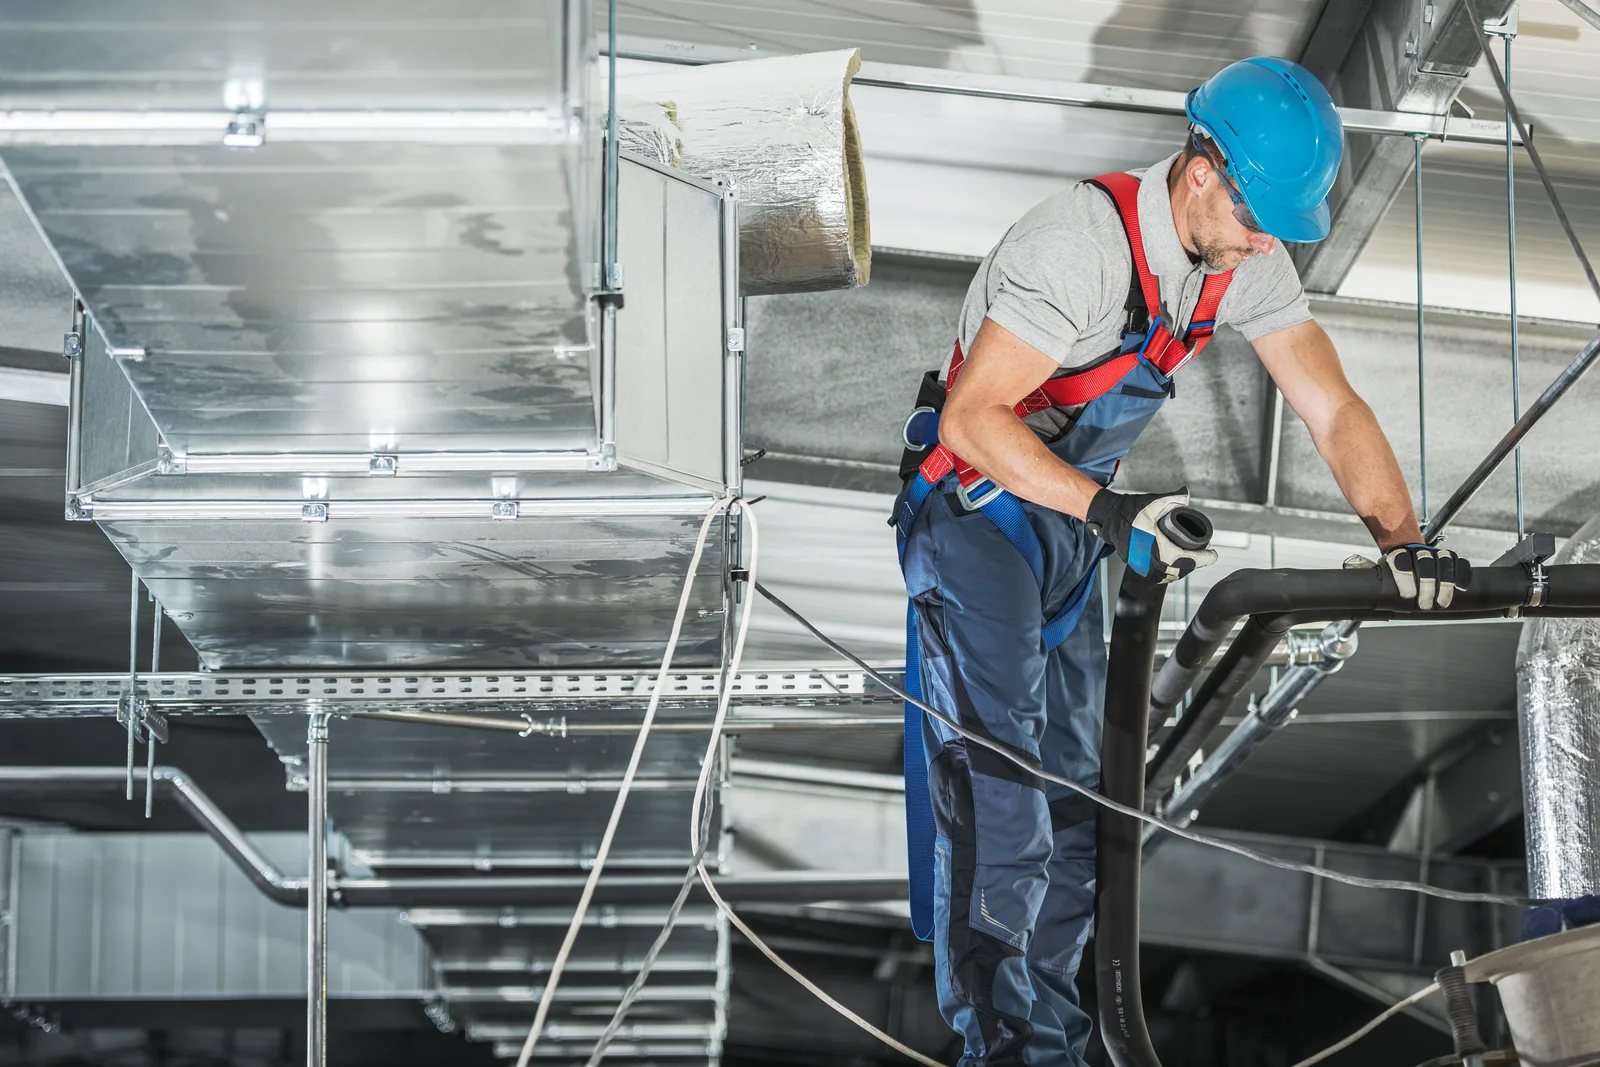
How much of your work happens on roofs and at height is its own driver. Setting and servicing rooftop units, rigging equipment onto a building, and working from lifts put technicians where a fall is a serious injury exposure, and that weighs on the workers compensation rate for the payroll doing it. The same work raises the general-liability stakes — a tool or component dropped from a roof is a third-party exposure that a ground-level service call does not carry. A carrier asks how much of your payroll works at height and what fall-protection program you run under OSHA standards, so documenting that program is one of the few ways to move this driver.
Completed operations — the signature HVAC cost driver
This is the exposure that defines the trade. An HVAC system keeps running in a building long after the crew leaves, and a defect in the work can become a claim days, months, or years later — a connection linked to a fire, a flue or heat-exchanger problem behind a carbon-monoxide claim, a failed condensate line that floods a finished ceiling. That is the products and completed-operations side of general liability, which pays for injury and damage caused by your completed work, and a general liability policy carries a separate aggregate limit for it. A carrier weighs how much install and changeout work you do, how your coverage handles claims that surface in later years, and your install-quality record. One honest note on the seam: the standard pollution exclusion removes most pollution losses from general liability, so a refrigerant release generally falls outside it; pollution liability is a separate policy, and whether your work warrants one is a question worth asking rather than assuming.
Fleet and equipment — the second signature driver
The other exposure that sets HVAC apart is the gear. The gauges, recovery machines, vacuum pumps, and the van of tools are a direct contractors equipment driver — an inland-marine line that follows the gear at the shop, in transit, and on the job site. How much equipment you run, what it is worth, and where it sits overnight are real inputs, because a van of gear is exactly what is stolen from a driveway or a site. The vans and trucks themselves are a commercial auto driver: how many vehicles you run, who drives them, how far they travel, and the driving records behind them. Scheduling your gear to its real value, securing the vans when they are parked, and screening drivers is where these drivers are won.
Claims history and how carriers read it
Your loss record is a driver you have been writing for years. A clean history opens more markets and prices better; a serious completed-operations, general liability, auto, or workers compensation loss narrows the field and raises the number, and a pattern of small claims can matter as much as one large one. Carriers read the story behind the losses too — a single claim followed by corrected install or commissioning procedures reads differently than repeated, similar incidents. The durable lever is operational discipline: documented install-quality and commissioning practices, combustion and carbon-monoxide safety checks, condensate-line discipline, refrigerant handling, and crew training all show up in the record a carrier prices.
The limits your contracts demand
What you buy is a driver too. The limits your commercial, general-contractor, and facility accounts require push you toward higher general liability limits and an umbrella that sits above your primary liability and auto policies, and higher limits cost more than lower ones. So do the contract terms that come with them — additional-insured status for ongoing and completed operations, and certificates delivered before you start. Whether your completed-operations aggregate matches your install volume, whether your tools are scheduled to value, and how your liability and auto limits are set all feed the number. None of these are places to under-buy blindly; they are places to buy deliberately, and to read the insurance section of a contract before you bid it — see what general contractors require from HVAC subs.
How state rules change HVAC insurance cost
The drivers above are national; the systems they run through are not. Workers compensation changes the most. In North Dakota, Ohio, Washington, and Wyoming, comp comes from a state fund rather than a private carrier, so that part of the program is priced by the fund and the rest of your coverage is built around it. In Texas, private employers choose whether to carry comp at all. Everywhere else, comp is placed in a competitive private market.
Licensing changes the program, too. Connecticut licenses heating, cooling, and sheet metal work statewide by license class and issues a contractor license only with evidence of workers compensation compliance. Texas ties its air conditioning and refrigeration contractor license to general liability coverage evidenced by a certificate on file. Montana has no statewide HVAC trade license and works through a general construction contractor license and local mechanical permits. And one credential never changes: under Section 608 of the federal Clean Air Act, every technician who could open a refrigerant circuit, apart from an apprentice working under close supervision, needs EPA Section 608 certification in Type I, II, III, or Universal form, whatever the state license says. Your own state’s guide sets these rules out in full — find it through the locations directory, where every state page links its cost guide.
How to get an accurate quote
The path to a real number is to describe your real operation. Tell a broker your payroll and the work it covers, your revenue and how much is new install versus service, your mix of residential and commercial work, how much of it happens at height, your completed-operations history, your equipment and vehicle list, your claims history, the limits your accounts require, and the states where you operate. From there a carrier with an appetite for the HVAC class can price it, and you can compare like with like instead of chasing a headline rate. For state-specific pictures, read the cost guides for California, Florida, New York, and the states above, or find your own in the locations directory. When you are ready, start a quote and tell us how your operation runs, or see how each line fits together in the coverage overview. The number at the end will reflect your business, which is the only number worth having.